The startup compliance calendar, FY 2026-27
A one-page visual calendar of the key compliance dates for an Indian private limited company in FY 2026-27: GST, TDS, advance tax, AGM, AOC-4, MGT-7, DIR-3 KYC and ITR.
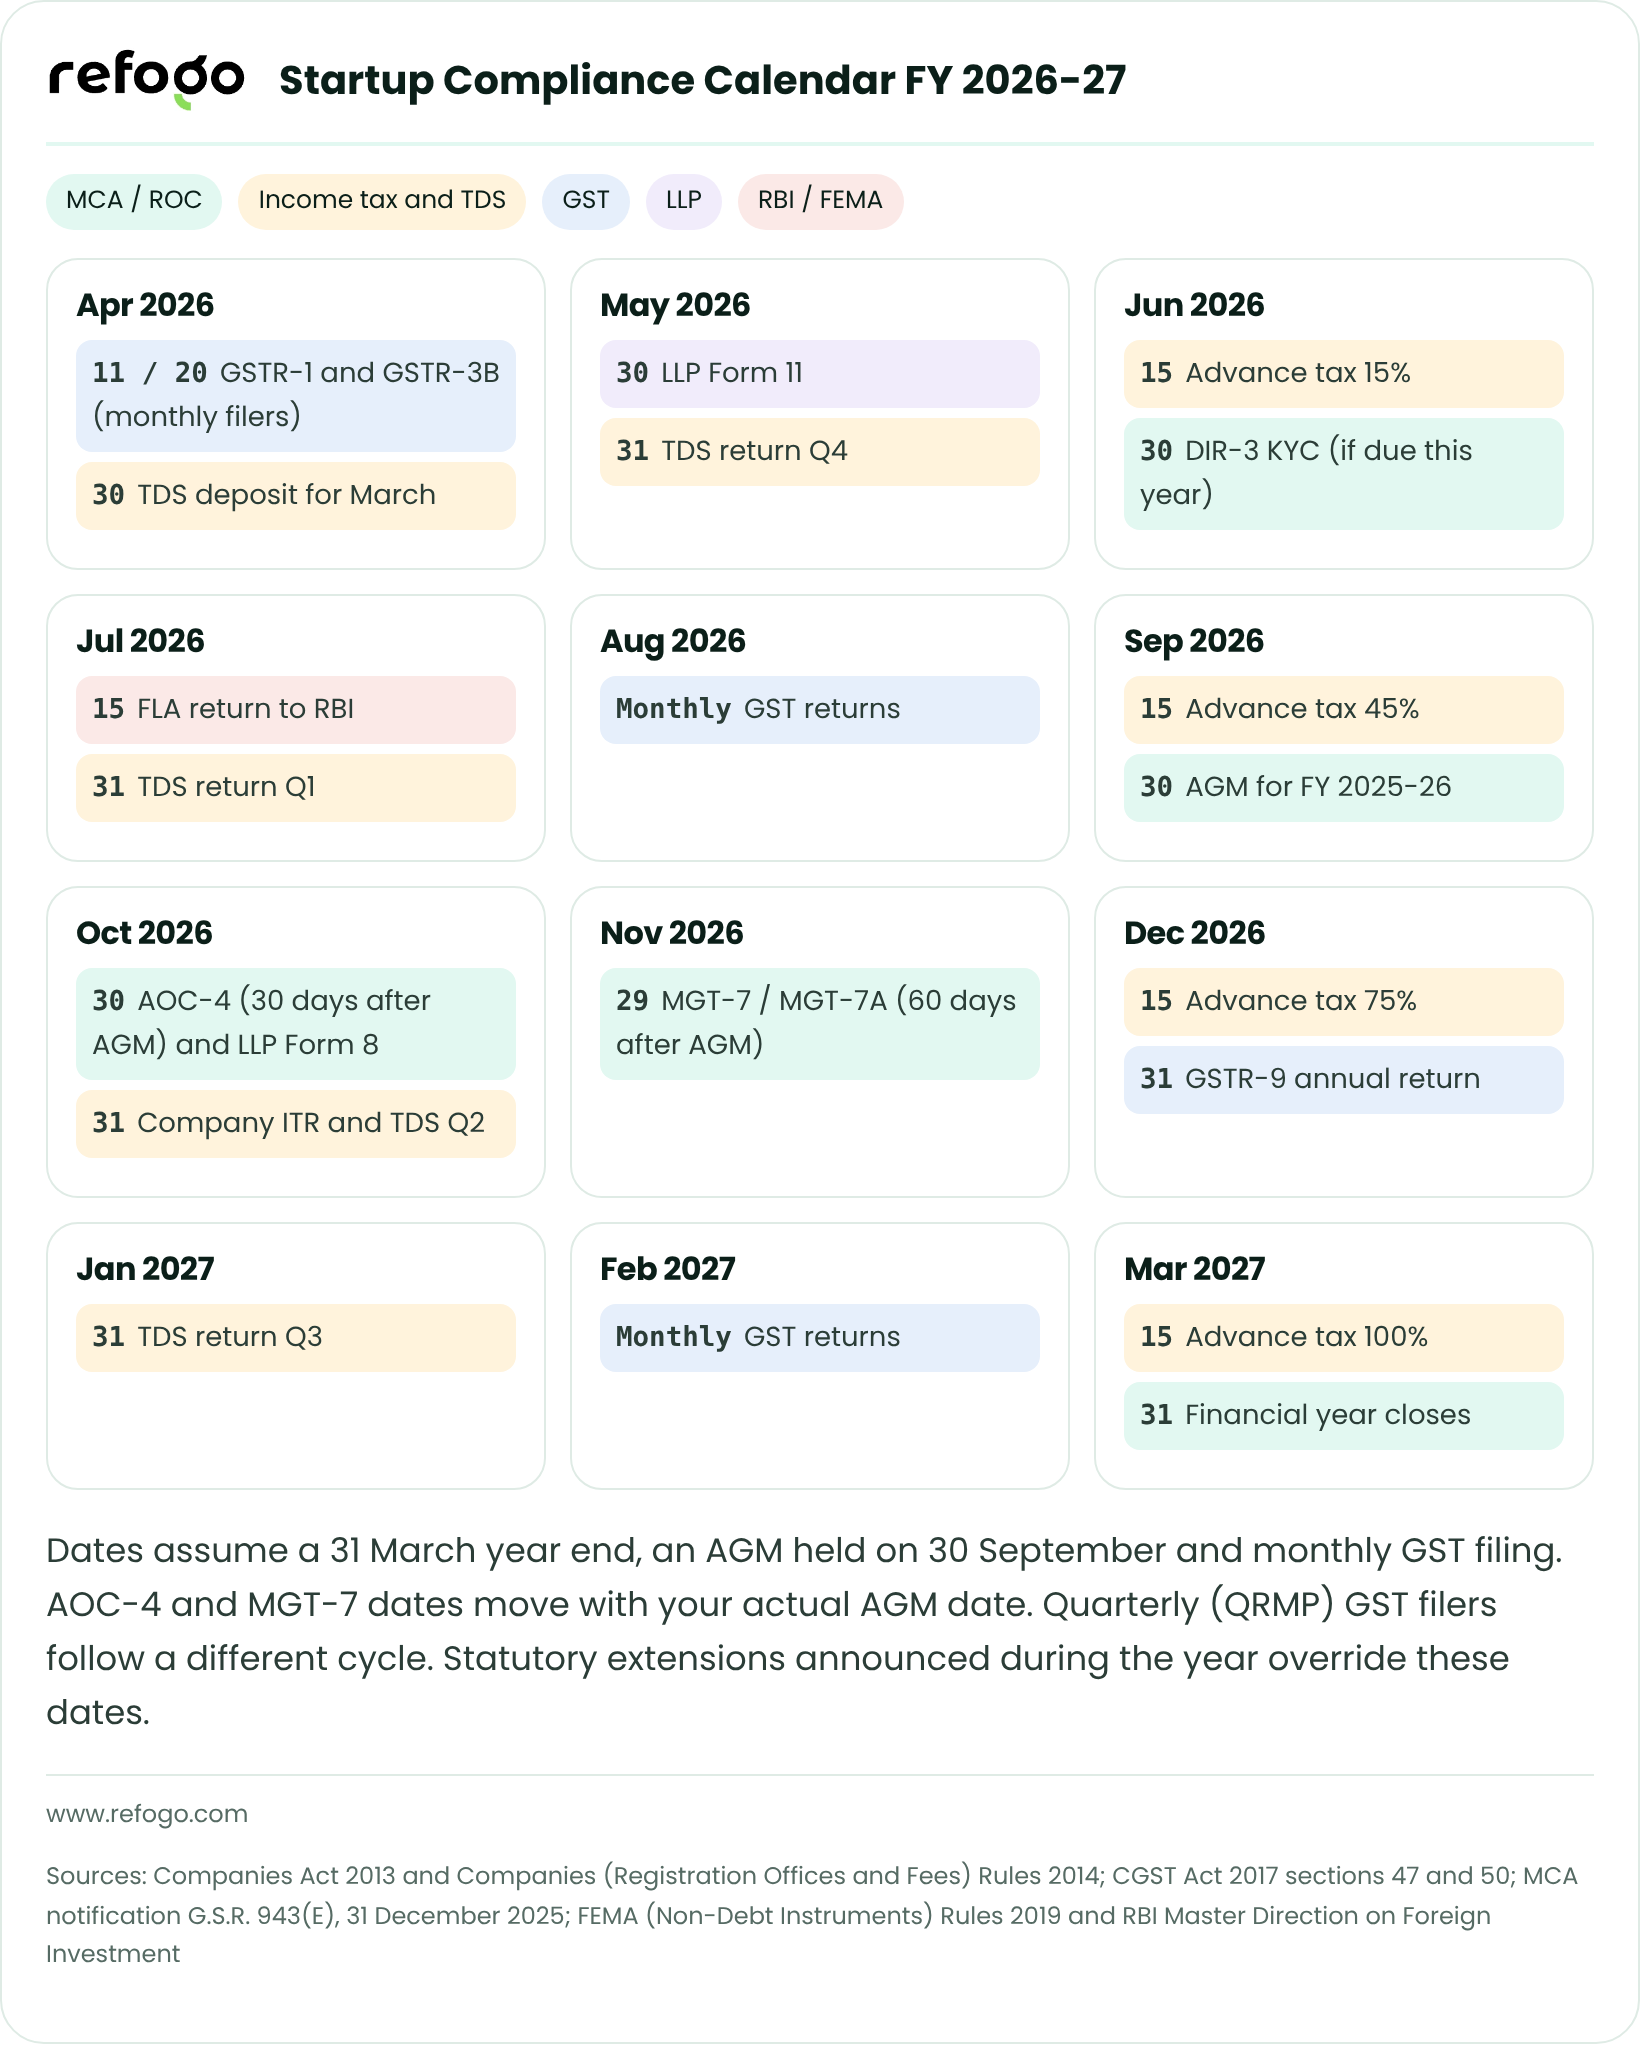
 Startup Compliance Calendar FY 2026-27
Apr 2026
- 11 / 20GSTR-1 and GSTR-3B (monthly filers)
- 30TDS deposit for March
May 2026
- 30LLP Form 11
- 31TDS return Q4
Jun 2026
- 15Advance tax 15%
- 30DIR-3 KYC (if due this year)
Jul 2026
- 15FLA return to RBI
- 31TDS return Q1
Aug 2026
- MonthlyGST returns
Sep 2026
- 15Advance tax 45%
- 30AGM for FY 2025-26
Oct 2026
- 30AOC-4 (30 days after AGM) and LLP Form 8
- 31Company ITR and TDS Q2
Nov 2026
- 29MGT-7 / MGT-7A (60 days after AGM)
Dec 2026
- 15Advance tax 75%
- 31GSTR-9 annual return
Jan 2027
- 31TDS return Q3
Feb 2027
- MonthlyGST returns
Mar 2027
- 15Advance tax 100%
- 31Financial year closes
Dates assume a 31 March year end, an AGM held on 30 September and monthly GST filing. AOC-4 and MGT-7 dates move with your actual AGM date. Quarterly (QRMP) GST filers follow a different cycle. Statutory extensions announced during the year override these dates.
Fixed-fee annual compliance with every date tracked.
www.refogo.comSources: Companies Act 2013 and Companies (Registration Offices and Fees) Rules 2014; CGST Act 2017 sections 47 and 50; MCA notification G.S.R. 943(E), 31 December 2025; FEMA (Non-Debt Instruments) Rules 2019 and RBI Master Direction on Foreign Investment
Related services
Sources
- Companies Act 2013 and Companies (Registration Offices and Fees) Rules 2014
- CGST Act 2017 sections 47 and 50
- MCA notification G.S.R. 943(E), 31 December 2025
- FEMA (Non-Debt Instruments) Rules 2019 and RBI Master Direction on Foreign Investment
General information only and not legal or tax advice. Figures are taken from the sources listed on the dates shown.
Common questions
When is the AGM deadline for FY 2026-27?
By 30 September 2026 for the year ended 31 March 2026, unless an extension is granted.
When are advance tax instalments due?
15 June, 15 September, 15 December and 15 March, at 15, 45, 75 and 100 percent of estimated tax.